- PM arrives in New York to attend 81st UNGA session |
- Jatri Kalyan Samity urges withdrawal of increased fuel prices |
- Global Diesel Shortage Likely to Persist Into 2027 |
- PM to Present Bangladesh Vision at UNGA: Mahdi |
- LDC graduation must strengthen, not constrain development: Titumir |
Global Diesel Shortage Likely to Persist Into 2027
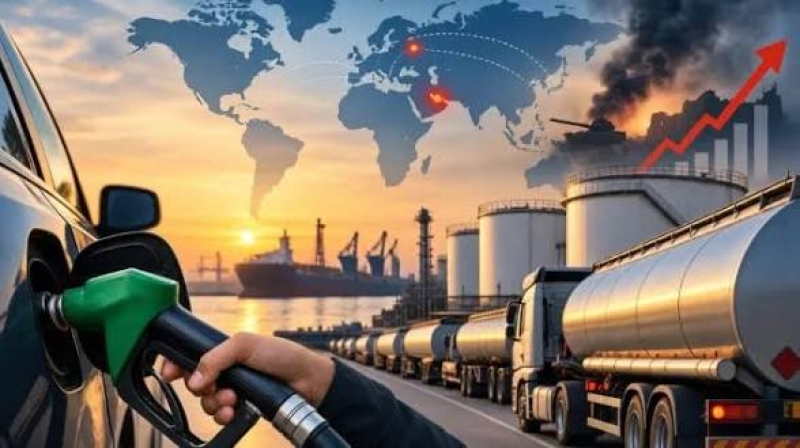
The global diesel shortage is unlikely to ease significantly before next year as conflicts in Iran and Ukraine continue to disrupt supplies, potentially keeping fuel prices elevated and adding pressure to economies worldwide.
The wars have severely disrupted diesel supplies from the Middle East and Russia, while inventories in major markets have fallen to historically low levels. The resulting supply squeeze has pushed diesel prices to record highs and increased costs across several major economic sectors.
Diesel is widely used in agriculture, manufacturing and heavy transportation, meaning prolonged shortages can raise operating and production costs well beyond the energy sector.
US Diesel Prices Top $6 a Gallon
The impact is particularly visible in the United States, where retail diesel prices surpassed $6 a gallon this month for the first time.
The higher prices are putting additional pressure on farmers, truck operators and other businesses that rely heavily on diesel. Rising transportation and production costs could also feed through to the prices of goods and services.
Diesel Storage Capacity Rising
Another indication of tight supply is emerging in the fuel-storage market.
Refiners and traders in North America have been declining to renew some diesel storage leases because there is not enough fuel available to fill the tanks. Data from storage broker The Tank Tiger showed that diesel storage capacity available for lease in North America and the Caribbean had risen to a four-year high of 13 million barrels for October, up from 11 million barrels in June.
US diesel inventories fell to 107.9 million barrels by September 11, the lowest level for that time of year since records began in 1982.
The combination of falling inventories and increasing storage availability suggests that market participants expect supplies to remain tight into at least the first quarter of next year.
Shortage May Persist Through 2027
The US Energy Information Administration expects US distillate fuel inventories—of which diesel is a major component—to remain below the five-year average through the end of 2026 and most of 2027.
European diesel inventories are also under pressure. Stocks at the Amsterdam-Rotterdam-Antwerp trading hub were 16% below the five-year average in July, according to market data cited in the report.
Additional diesel exports from China and strong refining margins could provide some relief. However, continued geopolitical tensions or unexpected refinery disruptions could trigger further price increases.
With diesel essential to transportation, agriculture and industrial production, prolonged supply constraints could continue to weigh on global economic activity and keep costs elevated into 2027.